Diesel repricing is pushing Saudi hauliers to defend margins with contract design, not hope. Logistics Middle East reports that as diesel prices have climbed, fleet operators have been forced to rethink routing, asset utilisation, and contract structures. It also notes that large logistics providers are increasingly shifting towards fuel surcharge models indexed to Aramco’s published rates, transferring part of the volatility to customers. This matters because for logistics operators, diesel remains the single largest variable cost after labour, and even incremental price changes translate into significant balance sheet pressure for large fleets operating long-haul routes between ports, industrial cities, and inland consumption centres.
The shift is not uniform across the market. The same Logistics Middle East analysis highlights that smaller hauliers, particularly owner-operators, face tighter margins and higher exposure, accelerating consolidation across the sector. In practice, that exposure shows up when rates are fixed but fuel is not. Oxford Economics describes how the effect on margins depends on a firm’s ability to pass higher diesel and freight costs downstream, shaped by competitive pressures, contract timing, and pricing flexibility. It adds that trucking firms have substantial direct exposure, but can recover some costs through fuel surcharges and frequent repricing. Where fixed-price contracts and intense competition collide, margin squeeze can land hardest.
Why Fuel Cost Pass-Through Works Better Than Fixed-Rate Freight
Fuel pass-through contracts are designed to keep base freight economics intact while letting fuel move with published benchmarks. A practical reason is timing. Intangles notes that fuel surcharges can lag price moves, meaning fleets absorb each increase before recovery catches up. The same source shows how severe volatility can be in other markets: US on-highway diesel swung from $3.459 a gallon in mid-January 2026 to a record $6.529 in the week of September 21, 2026, based on EIA weekly data. The point for Saudi operators is not the US price level, but the demonstrated risk of rapid moves that can break planning models when contracts are rigid.
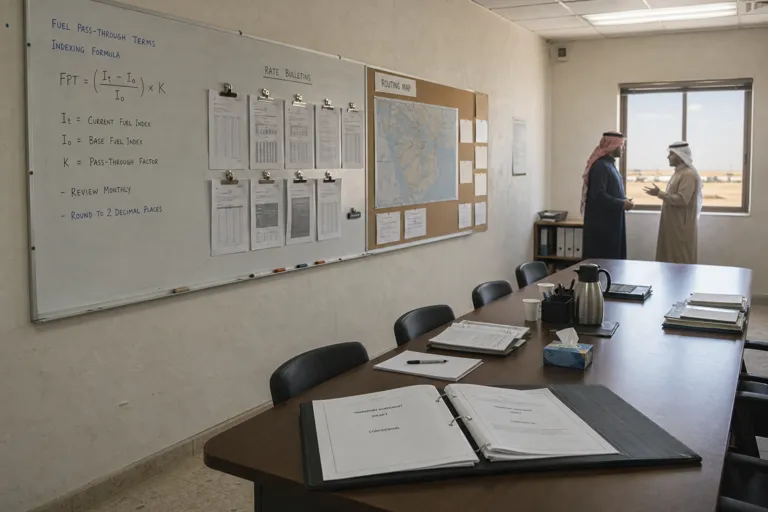
Good pass-through clauses still need discipline and clarity. WhyLoyalty explains the mechanism: carriers protect margins by applying a fuel surcharge, a percentage added on top of the base rate and indexed to the current cost of diesel, so it can move automatically without renegotiating every contract. Tank Transport also flags “surcharge discipline” as a differentiator, warning that the gap between fleets that can recover diesel and fleets that cannot may become more decisive. For the keyword topic of Saudi fuel price transport operators and diesel, indexing to an objective published rate is central to making recovery predictable for both shipper and carrier.
Pass-through contracts are only one layer of defense; operations decide whether margins merely survive or actually improve. TrucksOnTheMap, writing about European hauliers, quantifies why: idling, harsh acceleration, over-revving, and brake-rather-than-coast habits account for 8% to 12% of fuel consumption gaps on identical routes between top- and bottom-quartile drivers, and telematics coaching loops typically deliver 4% to 7% fuel savings within 6 months. That is Europe-specific, but it reinforces a universal truth also echoed by Intangles: the fastest costs a fleet can control include idle time, driver behavior, and fuel-related maintenance faults, and they must be managed per truck, not as fleet averages.
How do pass-through fuel clauses protect Saudi haulier margins?
Why are smaller Saudi hauliers more exposed to diesel repricing?
What makes fuel surcharge timing a risk for fleets?
How volatile can diesel prices get in a comparable market?
Beyond contracts, what operational levers reduce diesel spend?