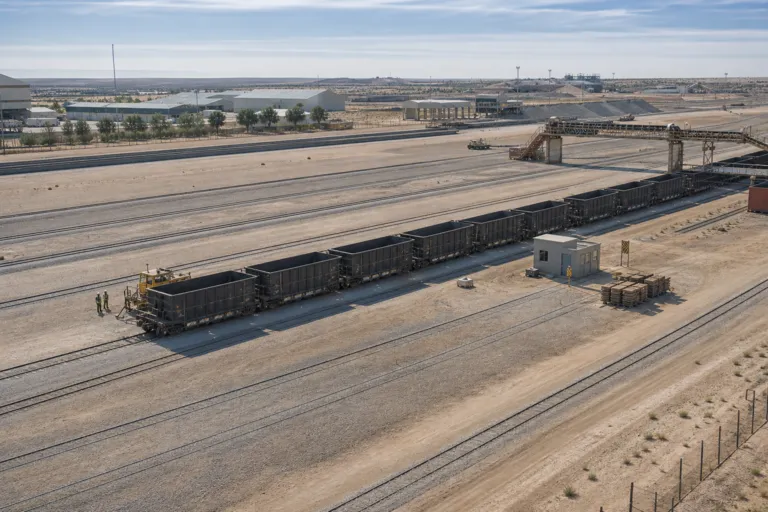
Saudi Arabia now has a public, time-stamped benchmark for rail freight: in Q3 2026, the Transport General Authority (TGA) reported 3.9 million tons of freight moved by rail, alongside 46,300 containers. The same quarter also logged more than 40.9 million rail passengers. For shippers, the freight figure is useful because it is specific to a single quarter and can be compared to the year-earlier quarter, when the report cited more than 4.09 million tons. The container count also has a year-on-year comparison in the same dataset: it was over 227,000 in Q3 2025, with no explanation offered for the change in 2026.
That quarterly snapshot should be read against Saudi Arabia’s broader freight modal context. One Saudi logistics source cites 331.3 million tonnes of freight moved through maritime routes in 2024, compared with 15.6 million tonnes by rail in the same year. The same reporting also references a 2025 Saudi Arabian Railways (SAR) figure of more than 30 million tonnes, positioning rail as a growing inland option even as shipping remains dominant in absolute volume. This is where the keyword topic matters: Saudi Railways freight 3.9 million tons is not just a headline, but a practical baseline for capacity planning, service design, and the realism of shifting cargo from road and sea into rail-linked corridors.
What the 3.9 Million-ton Quarter Signals for Network Readiness
Freight readiness is not only about mainline tracks. It is about connectors that turn separate assets into routing choices. One near-term milestone highlighted in Saudi rail progress reporting is the Riyadh Rail Link: a 35 km double-track connection between the North-South Railway and the Eastern Railway network, with SAR preparing to award the main design-and-build contract by the end of August and commercial proposals opened in August. In parallel, the Landbridge is described as being delivered in phases, with current reporting indicating completion before 2034. These timelines frame how quickly shippers can expect end-to-end routings that reduce reliance on long-haul trucking for cross-Kingdom moves.
Integrated logistics zones and port-to-inland transfers also shape whether rail freight volumes can scale beyond today’s benchmarks. In a Dammam-focused connectivity review, Nexdigm describes the Landbridge as spanning 1,300 km to connect the Red Sea to the Arabian Gulf and says it is expected to carry up to 3 million TEUs annually upon completion. The same source states the current rail freight network already handles 12.8 million tons per year, with expansions underway. These figures matter operationally because Landbridge performance depends on how effectively cargo is transferred between ports, yards, and rail services, not only on the existence of a cross-country line.
Finally, shippers should benchmark rail against the road-led reality of regional logistics, because that is the competitive environment rail must win in service reliability, not just infrastructure announcements. A 2025 snapshot of the GCC logistics market puts roadways as the leading transportation mode at 47.3% and 3PL as the leading model type at 51.8%. The same snapshot values the GCC logistics market at USD 114.56 Billion in 2025 and projects USD 182.01 Billion by 2034 at a CAGR of 5.01% during 2026–2034, while naming Saudi Arabia as the leading country market at 39.5% in 2025. Against that backdrop, the Q3 2026 3.9 million-ton freight result is best treated as a measurable starting point for Landbridge-era network performance, not the end state.
How much freight did Saudi Arabia’s railways move in Q3 2026?
How did the Q3 2026 freight figure compare with Q3 2025?
What is the Riyadh Rail Link and why does it matter for freight routing?
What do sources say about the Landbridge scope and timing?
Why is the Saudi Railways freight 3.9 million tons benchmark important for Landbridge readiness?