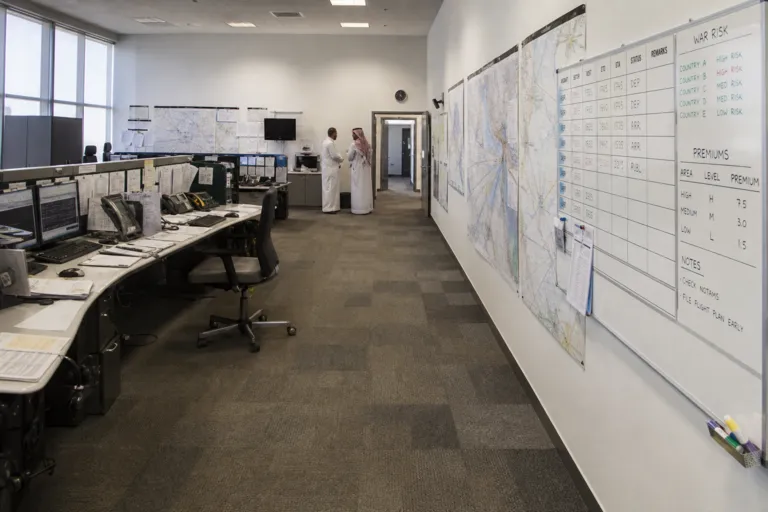
Insurance pricing for conflict-adjacent routes is moving fast, and Saudi aviation is being pulled into the same repricing cycle affecting the wider region. A March 2026 aviation risk review reported war-risk insurance premium spikes of 50–500% for aviation routes near the conflict zone, alongside underwriters tightening or repricing coverage for Gulf routes. It also stressed that standard policies exclude war damage, so specialist war-risk cover applies, often with restrictions, and it does not cover revenue losses from cancellations or rerouting—only direct physical damage. These constraints turn insurance into an operational limiter, not just a line item, when schedules, routings, and airport access are changing.
Saudi Arabia is now exploring a more direct response. The Financial Times reported on August 24, 2026 that Saudi Arabia has been holding discussions over state-backed war insurance as costs increase, with insurers raising prices or restricting coverage for ships and other firms in the region owing to the Iran conflict and Houthi attacks. While that reporting highlights marine and broader commercial exposures, it matters for aviation because the same war-risk logic drives capacity decisions in specialist markets. When private carriers face restricted cover or emergency terms, planning becomes harder, and the pricing signal can feed through into the total cost of operating near affected airspace.
How War-Risk Math Translates Into Aviation Route Decisions
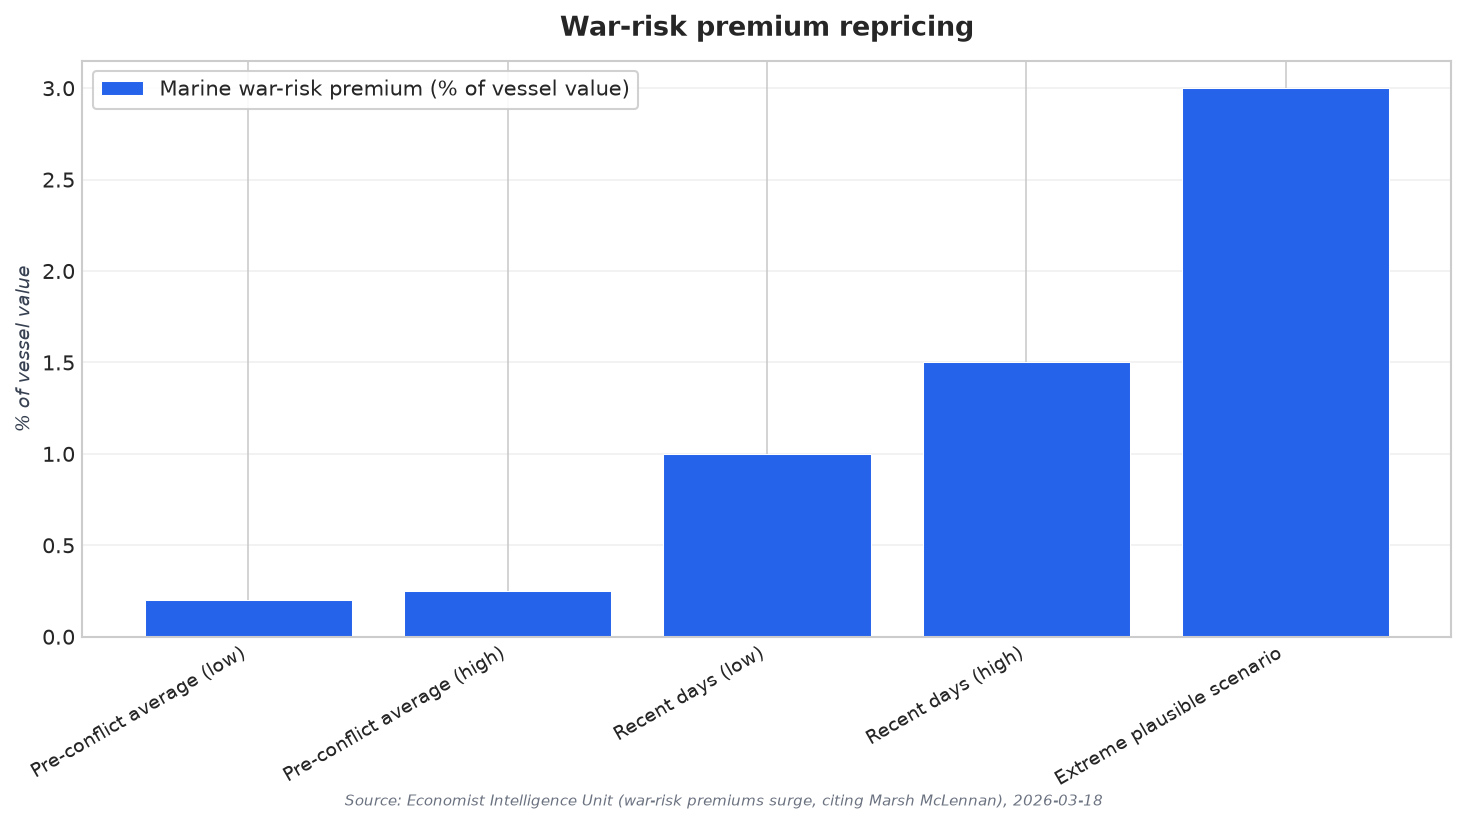
Marine markets show the mechanics of war-risk repricing in a way aviation decision-makers can compare against. Economist Intelligence Unit analysis cited US-based broker Marsh McLennan saying premiums that previously averaged 0.2–0.25% of a vessel’s value climbed to 1–1.5% in recent days. It noted most tankers are valued at US$200m to US$300m; at 0.25%, a Strait of Hormuz transit was roughly US$500,000–US$750,000 in war-risk insurance, while at 1% the cost per voyage could exceed US$2m. The same analysis described an “extreme but plausible” scenario of 3% of vessel value, reaching as high as US$7m for a single transit, underscoring how quickly a percentage change can become a material cash cost.
The wider market context also signals why war-risk cover remains sticky even when headlines improve. A June 2026 analysis focused on Hormuz argued that war-risk premiums of US$800K–2M per VLCC voyage need 12–36 months of claims-free data to fall, and that freight and insurance normalise on different timelines. It also stated that 60–70% of Saudi crude export volume moves on third-party chartered vessels whose operators arrange their own insurance independently of Aramco—an example of how risk costs can sit outside the control of a single national champion. For airlines, war-risk cover is similarly specialised, separately priced, and sensitive to claims and threat perceptions rather than short-term diplomacy.
A state backstop is being discussed because the goal is often stability, not eliminating risk. The EIU noted that government intervention could stabilise the insurance market but will not replace private capacity, and described how the US president indicated the US could provide naval escorts for tankers transiting the Strait of Hormuz and ordered the US International Development Finance Corporation to provide political risk insurance and financial guarantees for maritime trade in the Gulf. In Saudi Arabia, FT reporting points to talks about state-backed war insurance as costs jump and coverage tightens. For Saudi aviation war risk insurance, a backstop could function as a confidence signal to underwriters, helping prevent abrupt restrictions, smoothing renewals, and reducing the operational disruption that follows when war-risk terms shift faster than flight plans can adapt.
Why are war-risk insurance costs being repriced for Gulf-linked operations?
What does the 50–500% premium increase mean for airlines operating near the conflict zone?
How does Saudi aviation war risk insurance relate to Saudi Arabia’s state-backed insurance talks?
What figures show how fast war-risk pricing can change in practice?
Would a ceasefire quickly reduce war-risk insurance pricing?